
Do I Have Uninsured Motorist Coverage? How to Check Your Policy
The fastest way to find out is to pull your declarations page, the one- or two-page summary your insurer sent when you bought or renewed your policy, and look for a line labeled 'Uninsured Motorist,' 'UM,' or 'UM/UIM.' If that line is missing or blank, you may have rejected the coverage in writing, or it may never have been added. Under Fla. Stat. § 627.727, an insurer must offer UM coverage with every bodily-injury liability policy, but it is optional, and a Florida driver can lose it without ever realizing it.
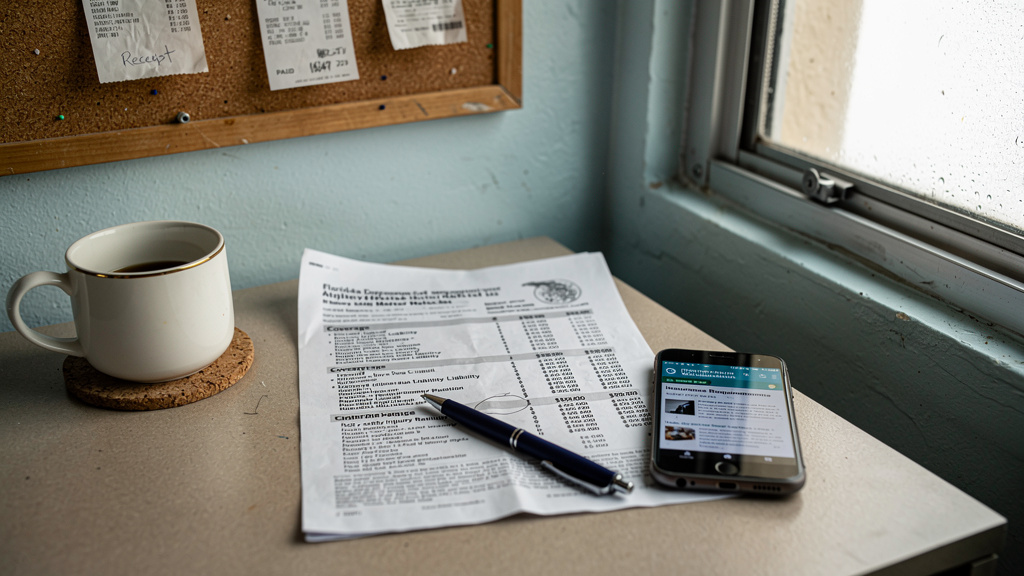
The fastest way to find out if you have uninsured motorist coverage is to look at your declarations page, the one- or two-page summary your insurer sends when you buy or renew your policy, and search for a line labeled “Uninsured Motorist,” “UM,” or “UM/UIM.” If that line is missing, blank, or shows $0, you may not have this coverage. Florida law requires insurers to offer UM with every bodily-injury liability policy, but it is optional. You can lose it without realizing it if you signed a written rejection form, even years ago.
Where do I find my declarations page, and what does it actually look like?
Your declarations page, often called the “dec page”, is the first one or two pages of your auto insurance policy. It lists every type of coverage you bought, the dollar limit for each, the premium charged, and which vehicles and drivers are covered. You can find it in your original policy packet, your insurer’s mobile app or online portal, or by asking your agent to email or mail you a copy. Do not rely on memory or your monthly bill. Many people believe they have “full coverage” only to learn later they have no uninsured motorist protection. “Full coverage” is not a legal term, it is marketing language and does not guarantee UM is included.
What words am I looking for on the declarations page?
Look for these exact labels: “Uninsured Motorist,” “UM/UIM,” or “UM/UIM Bodily Injury.” If you see a dollar amount next to any of these, like $10,000/$20,000 or $50,000, it means you have UM coverage at that limit. If the line is missing entirely, says “Rejected,” or shows $0, the coverage is likely not active. You will also see either “Stacked” or “Non-Stacked” next to the UM line. These terms matter for how your limits add up across multiple vehicles, but you do not need to understand the mechanics right now, just recognize the words. For a clear explanation of what stacking means, read our guide on stacked vs. non-stacked uninsured motorist coverage. These rules come from Florida Statute § 627.727.
What if UM doesn’t appear on my declarations page, did I reject it?
If UM is missing, check whether you signed a written rejection form. Under Florida law (§ 627.727(1)), you can only reject UM coverage by signing a form approved by the state. A verbal “no thanks” to an agent does not count. Ask your agent or insurer for a copy of the signed UM selection or rejection form, they may call it something slightly different, so confirm the exact name with them. If they cannot produce a valid, signed form, Florida law generally treats your policy as including UM coverage equal to your bodily-injury liability limits. Do not assume the declarations page tells the whole story. If the form is missing, incomplete, or inconsistent, the documents may need closer review before accepting the insurer’s position.
Should I also check the policies of relatives who live with me?
Yes. In many Hialeah households, the injured person does not own a car, but a spouse, parent, or other relative does. Florida law allows UM coverage to extend to “resident relatives” living in the same household, depending on how the policy defines who is insured. Get the declarations page for every auto policy held by anyone in your home. Then repeat the same search: look for “Uninsured Motorist,” “UM/UIM,” or “UM/UIM Bodily Injury.” Even if your own policy lacks UM, a family member’s might cover you. Florida Statute § 627.727 governs UM coverage, and under § 627.727(9) a non-stacked policy can limit coverage for household members in some situations. Coverage isn’t guaranteed under a relative’s policy, exclusions and definitions apply, but it is always worth checking.
How do I get the complete policy and the UM form from my agent or insurer?
Follow these steps: (1) Call or email your insurance agent or the carrier’s customer service line. (2) Ask specifically for three things: your complete auto policy, the declarations page for every relevant policy period, and the signed UM selection or rejection form on file. The form’s name may vary, confirm it with your carrier. (3) Request all documents in writing, by email or mail, to create a record. (4) If your agent cannot find the form, contact the insurer’s underwriting department directly. If you receive these documents and cannot interpret them, Wolfson & Leon reviews declarations pages and UM forms for injury victims, in Spanish, at our Hialeah office or remotely from your home.
I just had a crash and now I found UM coverage, what do I do next?
First, report the crash to your own insurer immediately. Delay can hurt your UM claim. Second, see a doctor within 14 days, Florida’s PIP rule (§ 627.736) cuts off your $10,000 in medical and wage benefits if you miss this window. Third, save every document the insurer sends: declarations pages, UM forms, claim letters. Fourth, know that the police crash report is confidential for 60 days (§ 316.066), except to you, your insurer, and your lawyer. Fifth, if your injury is serious, remember that a negligence lawsuit against the at-fault driver generally must be filed within two years from the crash date (for accidents on or after March 24, 2023) under § 95.11; a UM claim against your own insurer follows different deadline rules, so ask a lawyer about your timeline and do not wait. And you are not alone if you feel frustrated about being left with the bills after a crash caused by a driver with no insurance. If this is you, Wolfson & Leon reviews UM coverage questions for injury victims in Hialeah and Miami-Dade, in Spanish, at the office or at home.
Frequently asked questions
Does ‘full coverage’ automatically include uninsured motorist coverage in Florida?
No. “Full coverage” is not a legal term. It usually means you have more than just the state minimums, but it does not guarantee UM coverage. You must check your declarations page or UM rejection form to be sure.
Can I lose my UM coverage without knowing it?
Yes. If you signed a written UM rejection, even years ago, it can carry forward through every policy renewal. Many drivers forget they signed it or never realized what it meant.
What happens if my insurer says I rejected UM but can’t show me a signed form?
Under Florida law, if the insurer cannot produce a valid, signed UM rejection form, your policy is generally treated as if it includes UM coverage equal to your bodily-injury liability limits.
Can I use a family member’s UM coverage if I was hurt in a crash?
Possibly. If you live with a relative who has auto insurance, their UM coverage may extend to you, depending on the policy language and your relationship. Check their declarations page.
Does UM coverage pay to fix my car after an accident with an uninsured driver?
No. UM covers your medical bills, lost wages, and pain and suffering, but not vehicle damage. For car repairs, you would need collision coverage or to pursue the at-fault driver directly, if possible.
Related reading: The driver who hit me in Hialeah has no insurance. What now? · The 14-day PIP rule in Florida: what happens if you wait to see a doctor after a Hialeah car accident · How long do I have to file an injury lawsuit in Florida? The two-year rule after HB 837
Hurt in an accident in Hialeah? Call Wolfson & Leon at (305) 285-7071 for a free consultation. We speak Spanish, and there is no fee unless we win.
Key facts
- UM coverage is not required in Florida; an insurer must offer it, but a named insured can reject it, only by signing a written, state-approved form. A verbal 'no thanks' to an agent does not count. Source: Fla. Stat. § 627.727(1)
- If an insurer cannot produce a signed UM rejection or selection form, Florida law treats the policy as including UM coverage at limits equal to the policyholder's bodily-injury liability limits. Source: Fla. Stat. § 627.727(1)
- A significant share of Florida drivers are uninsured, so a serious crash with an at-fault driver who has no coverage is a realistic risk, not a remote one. Source: Insurance Research Council / Insurance Information Institute estimates cited in web research
- Florida requires only $10,000 in Personal Injury Protection and $10,000 in Property Damage Liability; it does not require bodily-injury liability coverage or UM coverage for most private passenger vehicles. Source: Fla. Stat. § 627.727; Fla. Stat. § 627.736
- A UM rejection signed on an earlier policy can carry forward to every renewal of that same policy, even years later, unless the named insured requests the coverage again in writing. Source: Fla. Stat. § 627.727(1); web research (SunKey Insurance)
Frequently asked questions
Does 'full coverage' automatically include uninsured motorist coverage in Florida?
'Full coverage' is not a legal term in Florida, it is a phrase agents and drivers use informally, and it does not guarantee that UM coverage is included. A policy can include comprehensive and collision and still lack UM if the named insured signed a rejection form. The only way to confirm whether UM is part of your policy is to pull the declarations page and look for the specific line labeled 'Uninsured Motorist,' 'UM,' or 'UM/UIM.' If that line is absent or marked rejected, UM is not in place regardless of what you were told at purchase.
Can I lose my UM coverage without knowing it?
Yes. Under Fla. Stat. § 627.727(1), a named insured can reject UM coverage by signing a written form, and that rejection can carry forward to every renewal of the same policy, sometimes for years. If you signed a rejection when your circumstances were different, a younger driver, a less expensive car, a different household, that rejection does not update itself automatically. Checking your current declarations page and asking your insurer for the signed UM form on file is the only reliable way to know where you stand.
What happens if my insurer says I rejected UM but can't show me a signed form?
Under Florida law, if an insurer cannot produce a valid signed UM rejection or selection form, the coverage is generally treated as part of the policy at limits equal to the bodily-injury liability limits, even if the declarations page does not show it. This rule comes from Fla. Stat. § 627.727(1). Whether a specific form is legally sufficient depends on its content and how it was obtained, so if your insurer tells you that you rejected UM but cannot produce the paperwork, that situation deserves a careful review of the actual documents before you accept the insurer's position.
Can I use a family member's UM coverage if I was hurt in a crash?
Possibly. Florida UM policies typically extend coverage to resident relatives, spouses and other family members who share the same household as the named insured. If you were injured and do not have your own UM coverage, or if your own limits are low, a policy held by a spouse or relative who lives with you may provide additional coverage. Coverage depends on how the specific policy defines 'insured' and 'resident relative,' so you must pull each household policy's declarations page and confirm the definitions in the policy itself.
Does UM coverage pay to fix my car after an accident with an uninsured driver?
No. Florida UM coverage is bodily-injury coverage, it is designed to pay for medical expenses, lost wages, pain and suffering, and similar personal injury damages when the at-fault driver has no or insufficient liability insurance. Damage to your vehicle after a crash with an uninsured driver is typically addressed through your own collision coverage, not UM. If you do not carry collision coverage, you may have limited options to recover the vehicle damage from an uninsured at-fault driver.
This article is general information about Florida law, not legal advice, and reading it does not create an attorney-client relationship. Every case is different and past results do not guarantee a similar outcome. For advice about your situation, call Wolfson & Leon at (305) 285-7071 for a free consultation.
Also available in: Versión en español
 Personal injury
Hit by an Uninsured Driver in Florida With No UM Coverage: What's Left?
Even without uninsured motorist coverage, you are not completely out of options: your own PIP coverage still pays first, a relative's UM policy may…
 Personal injury
How to Get Your Miami-Dade Crash Report When the Other Driver Had No Insurance
After a crash in Miami-Dade, the agency that responded, Hialeah Police, the Miami-Dade Sheriff's Office, or FHP, files a crash report that you can…
 Personal injury
Florida's Serious Injury Threshold: When Can You Sue for Pain and Suffering?
Florida law bars you from suing the at-fault driver for pain and suffering unless your injury falls into one of four categories defined in Fla.…