
Who Pays My Medical Bills After an Uber Accident in Florida?
After an Uber accident in Florida, your own PIP insurance pays your first medical bills, up to $10,000 if a doctor confirms an emergency medical condition, or only $2,500 without that finding, regardless of who caused the crash. Once PIP runs out, the coverage that kicks in depends on what the Uber driver was doing in the app at the exact moment of impact: an accepted ride triggers a $1 million liability policy; a driver merely logged in but waiting triggers lower minimums. If the at-fault driver had no or too little coverage, your own uninsured motorist policy or Uber's UM coverage may also apply.
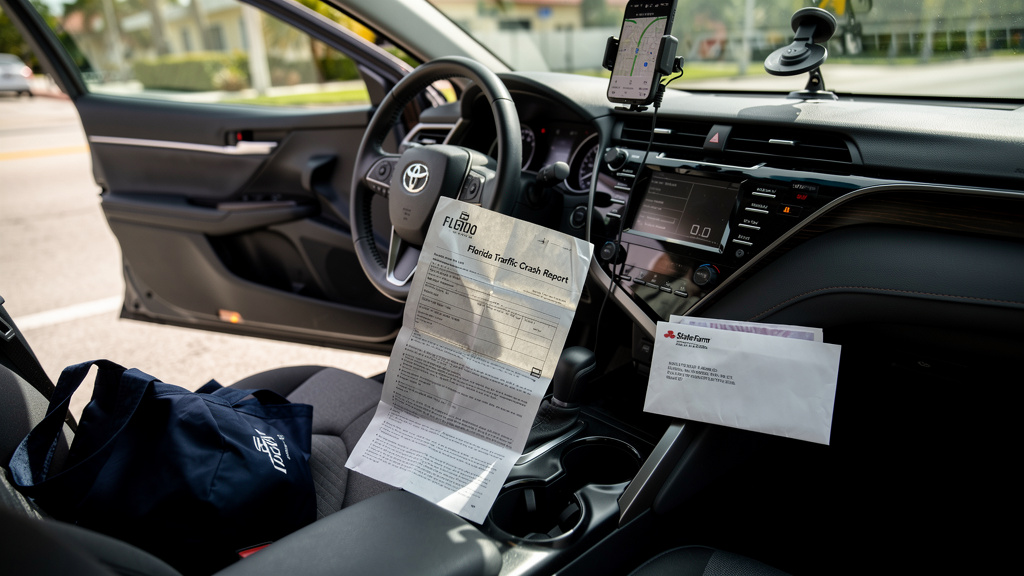
After an Uber accident in Florida, your own PIP insurance pays your medical bills first, up to $10,000 if a doctor documents an emergency medical condition or only $2,500 without that finding, regardless of who caused the crash. Once PIP runs out, or if your bills exceed what PIP covers, additional coverage layers exist: health insurance, the Uber driver’s applicable liability policy, and your own uninsured motorist coverage. What many people get wrong is this: Florida’s no-fault system does not mean the at-fault driver never matters. It only means PIP pays first. The at-fault party’s liability policy and your right to sue for pain and suffering are still in play.
Who Pays My Medical Bills After an Uber Accident in Florida?
Under Fla. Stat. § 627.736, Florida PIP pays 80 percent of reasonable medical bills and 60 percent of lost wages, up to $10,000 when a treating physician documents an emergency medical condition, or up to $2,500 without that finding. PIP pays regardless of fault.
Under Fla. Stat. § 627.736(4)(e), your own PIP policy pays first, even if you were a passenger in the Uber. If you have no policy, a household relative’s policy comes next. Only if neither exists does the PIP tied to the vehicle you were riding in become relevant. Uber’s coverage does not jump the line.
After PIP, your health insurance can pick up the unpaid 20 percent and any costs beyond PIP limits. If the Uber driver was at fault, the applicable Uber liability policy can then apply; if another driver caused the crash, that driver’s liability policy is the source. If the at-fault driver had no insurance or too little to cover serious injuries, your own uninsured motorist (UM) policy or Uber’s UM coverage may also apply. Each of these layers matters when your bills are serious.
What Does the Uber Driver’s App Status Have to Do With My Bills?
The driver’s app status at the exact moment of impact determines which insurer is on the hook and for how much. Under Fla. Stat. § 627.748, there are three distinct periods.
Period 1: App off. Only the driver’s personal auto policy applies. Florida does not require personal policies to carry bodily injury liability at all, so coverage may be very limited or nonexistent.
Period 2: App on, waiting for a ride request. Florida requires at least $50,000 per person and $100,000 per incident in bodily injury liability, plus $25,000 in property damage, plus PIP.
Period 3: Ride accepted through passenger drop-off. Florida requires at least $1 million in primary liability coverage plus PIP and UM/UIM. This applies from the moment the driver accepts the trip, including while driving to pick up the passenger.
One screenshot of the driver’s app at the time of impact can be the difference between a $50,000 limit and a $1 million limit. Under Fla. Stat. § 627.748, Uber must provide any party directly involved in the crash, upon request, the precise times the driver logged on and off the app for the 12 hours before and after the accident, without requiring a lawsuit first. If the driver’s personal policy has lapsed or does not meet the required minimums, Uber’s policy must provide the required coverage from the first dollar.
What Does Florida Law Actually Require After an Uber Crash?
Several statutes govern an Uber accident claim in Florida from start to finish.
PIP coverage (Fla. Stat. § 627.736): 80 percent of medical bills and 60 percent of lost wages, up to $10,000 with an emergency medical condition finding, $2,500 without one. The 14-day PIP treatment deadline is absolute. Miss it and you forfeit all PIP benefits.
Emergency medical condition (Fla. Stat. § 395.002(8)): Acute symptoms severe enough that without immediate care the patient’s health could be in serious jeopardy, or they could suffer serious impairment of bodily function or organ dysfunction. The treating physician makes this call, not the insurance adjuster.
Pain and suffering threshold (Fla. Stat. § 627.737(2)): To recover pain and suffering, mental anguish, or loss of enjoyment of life from the at-fault party, your injury must be permanent within reasonable medical probability, involve significant and permanent loss of an important bodily function, or result in significant and permanent scarring or disfigurement. Read more about Florida’s serious injury threshold for pain and suffering.
Modified comparative negligence (Fla. Stat. § 768.81(6)): Your recovery is reduced by your share of fault and barred only if you are more than 50 percent at fault. For passengers who had no control over the vehicle, this threshold is rarely an issue.
UM coverage (Fla. Stat. § 627.727): Uninsured motorist coverage is optional but must be rejected in writing. Many policyholders unknowingly keep it.
Crash report confidentiality (Fla. Stat. § 316.066): The crash report is confidential for 60 days, but parties, their insurers, and their lawyers are entitled to a copy during that window.
Lawsuit deadline (Fla. Stat. § 95.11): For crashes on or after March 24, 2023, you have two years from the date of the crash to file a negligence lawsuit.
What Should I Do Right Now, Step by Step?
-
Call 911 and get a police report. Do not leave the scene without one.
-
See a doctor the same day, or within 14 days at the absolute latest. Under Fla. Stat. § 627.736, missing that deadline forfeits all PIP benefits entirely. Miami-Dade and Hialeah residents can be treated at Jackson Memorial’s Ryder Trauma Center, Palmetto General, or Hialeah Hospital.
-
Screenshot the Uber app before closing it. Capture the ride confirmation, the route, and the driver’s name and photo. This documents which app-status period applies to your crash.
-
Photograph everything at the scene. Vehicle damage, your visible injuries, the road, traffic signals, and any skid marks.
-
Collect contact information from all drivers, passengers, and witnesses.
-
Do not give a recorded statement to any insurance adjuster before speaking with a lawyer. Adjusters may argue that a gap in treatment means your injury came from something other than the crash.
-
Report the crash to Uber through the app immediately.
-
Notify your own auto insurer and open a PIP claim. Your policy pays first.
-
Obtain the crash report. Under Fla. Stat. § 316.066, you are entitled to it even during the 60-day confidentiality window.
-
Contact a personal injury lawyer before accepting any settlement offer. See what to bring to an Uber accident lawyer consultation so you are prepared from the first call.
When Should I Call a Lawyer About My Uber Accident?
Call a lawyer immediately, before the insurer denies you anything, if any of the following apply.
You were taken to the emergency room or admitted to a hospital. Your bills have already exceeded $2,500 or look likely to. You cannot work because of your injuries. An adjuster has called and asked for a recorded statement. You have received a settlement offer. You are unsure whether the crash happened during Period 1, 2, or 3 of the driver’s app status. More than one insurance company is involved and you are being bounced between them with no clear answer on who pays. The at-fault driver may have been uninsured or underinsured. An insurer is disputing whether your injury qualifies as an emergency medical condition.
These are not edge cases. They are the situations that show up regularly in online discussions by crash victims: people facing a large hospital balance heading to collections, not knowing why two insurance companies are calling, or being told PIP is all they get. That is often incorrect.
A lawyer can formally request Uber’s app log data under Fla. Stat. § 627.748 and can obtain the crash report under Fla. Stat. § 316.066 during the confidentiality period. These are things you cannot easily do on your own, and the data degrades over time. Uber’s insurer has experienced adjusters and a defense team. They are not going to pay more than they are pressured to pay.
The lawsuit deadline under Fla. Stat. § 95.11 is two years from the date of the crash for injuries on or after March 24, 2023. Two years sounds like a long time. It is not, once you account for gathering records, obtaining expert opinions, and building a case. Wolfson & Leon handles Uber and rideshare accident cases in Hialeah and throughout Miami-Dade County. There is no fee unless we win.
What If the Other Driver, Not the Uber Driver, Caused the Crash?
Being a passenger in an Uber when a third party causes the crash does not cut off your access to Uber’s coverage. Once a ride has been accepted (Period 3), Uber’s UM/UIM coverage under Fla. Stat. § 627.748 may apply if the at-fault third-party driver had no insurance or too little insurance to cover serious injuries.
As an injured passenger in that situation, you may simultaneously pursue: your own PIP for initial bills under Fla. Stat. § 627.736; the at-fault third-party driver’s bodily injury liability policy; Uber’s UM/UIM coverage if the third party’s coverage falls short, under Fla. Stat. § 627.727 and § 627.748; and your own UM policy if you have one and did not reject it in writing.
The permanent injury threshold under Fla. Stat. § 627.737(2) applies as the gate to pain and suffering recovery from any of these sources. When the at-fault driver has left the scene or carries no insurance, the result is exactly the scenario people describe online: a large hospital bill moving toward collections with no clear answer on who pays. UM coverage exists specifically to prevent that outcome. If the at-fault driver who rear-ended your Uber on the Palmetto Expressway had no insurance, your UM claim and Uber’s UM policy are the two places to look. Read more about your options when hit by an uninsured driver.
Frequently Asked Questions
I was a passenger in an Uber that got rear-ended in Miami. Whose insurance am I supposed to deal with?
Start with your own PIP policy under Fla. Stat. § 627.736(4)(e), which pays first regardless of fault, up to $10,000 with an emergency medical condition finding. After PIP, the at-fault driver’s bodily injury liability policy is the primary source for damages beyond PIP limits. If that driver had no insurance or too little, Uber’s UM/UIM coverage under Fla. Stat. § 627.748 may apply during an active ride, and your own UM policy may apply as well.
What if my Uber driver wasn’t at fault? Can I still recover from Uber’s insurance?
Yes, in certain situations. If a third party caused the crash during an active ride, Uber’s UM/UIM coverage under Fla. Stat. § 627.748 can apply when the at-fault driver had no insurance or not enough to cover your injuries. You would still pursue that at-fault driver’s policy first, but Uber’s UM/UIM coverage exists precisely for situations where that policy falls short.
What happens if I don’t see a doctor right away after an Uber crash?
If you do not begin medical treatment within 14 days of the crash, you lose all PIP benefits under Fla. Stat. § 627.736, the entire $10,000 you already paid for through your premium. Beyond PIP, a gap in treatment gives insurers an argument that your injury was caused by something other than the crash. See a doctor the same day if you can, and no later than within 14 days.
What does it mean that Florida is a no-fault state? Does the at-fault driver still matter?
Florida’s no-fault system means your own PIP pays your initial medical bills regardless of who caused the crash. It does not mean the at-fault driver is off the hook. Once PIP runs out, or if your injuries meet the permanent-injury threshold under Fla. Stat. § 627.737(2), you can pursue the at-fault driver’s liability policy for damages including pain and suffering.
How long do I have to file a lawsuit after an Uber accident in Florida?
For crashes on or after March 24, 2023, you have two years from the date of the crash to file a negligence lawsuit under Fla. Stat. § 95.11. Missing that deadline generally means losing the right to sue entirely. Two years passes quickly when you account for medical treatment, gathering records, and building a case, so it is worth speaking with a lawyer well before that window closes.
Complete guide: Uber and Lyft Accidents in Florida: What Hialeah Riders Need to Know
Hurt in an accident in Hialeah? Call Wolfson & Leon at 305-965-3766 for a free consultation. We speak Spanish, and there is no fee unless we win.
Key facts
- Florida PIP pays 80 percent of reasonable medical bills and 60 percent of lost income up to $10,000 when a doctor documents an emergency medical condition, but only up to $2,500 without that finding. Source: Fla. Stat. § 627.736
- You must begin medical treatment within 14 days of the crash or you forfeit all PIP benefits entirely. Source: Fla. Stat. § 627.736
- When a rideshare driver has accepted a ride and is en route or carrying a passenger, Florida law requires at least $1 million in primary liability coverage for death, bodily injury, and property damage. Source: Fla. Stat. § 627.748
- The injured person's own PIP pays first; only if they have no policy does coverage shift to a household relative's policy, and only if neither exists does the PIP tied to the vehicle they were in become relevant. Source: Fla. Stat. § 627.736(4)(e)
- For crashes on or after March 24, 2023, an injured person has two years from the date of the crash to file a negligence lawsuit in Florida. Source: Fla. Stat. § 95.11
Frequently asked questions
I was a passenger in an Uber that got rear-ended in Miami. Whose insurance am I supposed to deal with?
Your own PIP policy pays your first medical bills under Florida's no-fault rules, regardless of which driver caused the crash, so open a PIP claim with your own insurer first. Because you were on an active ride, Uber's $1 million liability policy is also in the picture: if your Uber driver was at fault, you can pursue that policy for serious injuries once PIP is exhausted; if the other driver was at fault, you pursue that driver's liability policy, and if their coverage is insufficient, Uber's UM/UIM coverage may fill the gap. You may be dealing with two or three insurers at once, which is one reason having a lawyer communicate on your behalf matters.
What if my Uber driver wasn't at fault, can I still recover from Uber's insurance?
Yes. Under Fla. Stat. § 627.748, Uber's uninsured and underinsured motorist coverage applies during an active ride, alongside its $1 million liability coverage, precisely for situations where another driver caused the crash and that driver has no insurance or too little to cover serious injuries. Your claim would go first to the at-fault driver's liability policy, and then to Uber's UM/UIM policy for any gap. Your own PIP still pays your initial medical bills regardless of who was at fault.
What happens if I don't see a doctor right away after an Uber crash?
If you do not begin medical treatment within 14 days of the crash, you lose all PIP benefits under Fla. Stat. § 627.736, you will receive nothing from PIP, not even the $2,500 minimum tier. Insurance adjusters also use a gap in treatment to argue that your injury was caused by something other than the crash, which can hurt a broader bodily injury claim. Go to an emergency room or urgent care the same day if possible, and make sure the treating provider documents your symptoms in detail.
What does it mean that Florida is a no-fault state? Does the at-fault driver still matter?
No-fault means your own PIP pays your initial medical bills regardless of who caused the crash, you do not have to wait for a fault determination to start treatment and get reimbursed. However, the at-fault driver absolutely still matters for anything beyond PIP. If your injuries are serious enough to meet the permanent-injury threshold under Fla. Stat. § 627.737(2), you can pursue pain and suffering, future medical costs, and lost earning capacity from the at-fault party's liability policy. No-fault does not protect an at-fault driver from a bodily injury claim; it only determines who pays your first set of bills.
How long do I have to file a lawsuit after an Uber accident in Florida?
For crashes that happened on or after March 24, 2023, Florida law gives you two years from the date of the accident to file a negligence lawsuit under Fla. Stat. § 95.11. Do not wait until the deadline is close, app logs, trip records, witness memories, and medical documentation are easier to obtain and more complete shortly after the crash. A different deadline may apply to a UM claim against your own insurer, so confirm the specific timeline with a lawyer if negotiations stall.
This article is general information about Florida law, not legal advice, and reading it does not create an attorney-client relationship. Every case is different and past results do not guarantee a similar outcome. For advice about your situation, call Wolfson & Leon at 305-965-3766 for a free consultation.
Also available in: Versión en español
 Uber and Lyft accidents
How Rideshare Accident Settlements Work in Miami-Dade, Florida
A rideshare accident settlement in Miami-Dade is shaped by five things: how serious and permanent your injury is, what your medical bills and lost…
 Uber and Lyft accidents
Uber and Lyft Accidents in Florida: What Hialeah Riders Need to Know
Which insurance pays after an Uber or Lyft crash in Florida depends almost entirely on what the driver's app was doing at the moment of impact.…
 Uber and Lyft accidents
Can You Get Pain and Suffering After an Uber or Lyft Accident in Florida?
Yes, but only if your injury meets Florida's permanent-injury threshold. Under Fla. Stat. § 627.737(2), you cannot recover pain and suffering from…